When Does an ORC System on a Ship Qualify for the Energy Investment Allowance (EIA)?
Author: Jeroen Berger • Publication date:
An ORC installation on a ship may, subject to conditions, qualify for the Energy Investment Allowance (EIA), but the inclusion of this technology in the Dutch Energy List does not automatically mean that every maritime investment qualifies for this deduction. An installation based on the Organic Rankine Cycle (ORC) can form part of a waste heat recovery system (WHRS) through which heat from sources such as exhaust gases or engine cooling water is converted into mechanical or electrical energy. The 2026 Energy List includes a specific description of an Organic Rankine Cycle or Kalina cycle under business asset code 221102. However, for the EIA to apply, it must be established whether the particular installation falls under an appropriate business asset code, which entity is treated as the investor for tax purposes and whether certain exclusions apply.
For companies operating seagoing ships, the Dutch tonnage tax scheme is particularly important. For the part of the business to which this scheme applies, there is no entitlement to an investment deduction. The qualifying investment costs, technical design and period within which the investment is notified to the Netherlands Enterprise Agency (RVO) are also decisive. It is therefore advisable to check tax eligibility before a binding investment commitment is made. The assessment below is based on the Energy List and applicable tax conditions for 2026.
When Can an ORC Installation on a Ship Fall Within the EIA?
The Energy Investment Allowance is a Dutch tax scheme for investments in designated energy-saving business assets and sustainable energy technologies. A business that meets the conditions may deduct an additional proportion of the qualifying investment costs from taxable profit. For an ORC, this scheme may be relevant because electricity production from waste heat can reduce the need for other energy generation on board. However, whether such an investment actually qualifies for the EIA does not depend solely on the energy savings achieved.
An ORC uses heat from a suitable source to evaporate an organic working fluid. The vapour drives an expander to produce mechanical power, which a generator can convert into electricity. After expansion, the working fluid condenses and is pumped back to the hot side of the cycle. When the electricity generated reduces the load on existing generating sets, fuel consumption can decrease. The actual savings depend, in this context, on the available heat supply, net electricity generation and which source consequently supplies less power.
However, demonstrable fuel savings are not automatically sufficient to qualify for the EIA. The scheme imposes separate conditions on how the asset meets the technical description, the investor's tax position and the way in which the investment is notified. Tax exclusions may also apply, even when the installation is technically suitable for generating electricity from waste heat. A distinction must therefore be made between an ORC that performs well in energy terms and an investment that actually meets the tax conditions.
An installation may, for example, save sufficient fuel but still fall outside the EIA when the investment is attributable to a part of the business to which the tonnage tax scheme applies. Conversely, an ORC investment by a qualifying business may be eligible for the EIA, provided that the technical design falls under a permitted business asset code and the investment is notified correctly and on time. For a sound investment decision, these conditions must be assessed together. The installation's commercial name or a general ORC product specification provides insufficient certainty for this purpose.
What Does the Energy List 2026 Require for an Organic Rankine Cycle?
The Energy List is established annually and describes which business assets may, under the applicable conditions, qualify for the Energy Investment Allowance. The 2026 Energy List applies to purchase commitments made in 2026. Business asset code 221102 covers the Organic Rankine Cycle or Kalina cycle under Energy Reuse in the Processes category. The stated purpose is the conversion of waste heat into mechanical or electrical energy. The code thus concerns a specific application of heat recovery, but also imposes conditions on the components that make up the asset.
The description lists a condenser, evaporator, pump and turbine as components of the installation. A separator, heat exchanger, generator and connection to the electricity grid are also listed as optional components. The distinction between these core components and those designated as optional is important, because the business asset code does not describe only the outcome of energy recovery. The technical configuration through which this outcome is achieved also forms part of the description. For an ORC on board, it must therefore be established which components are actually present and how they work together in the thermodynamic cycle.
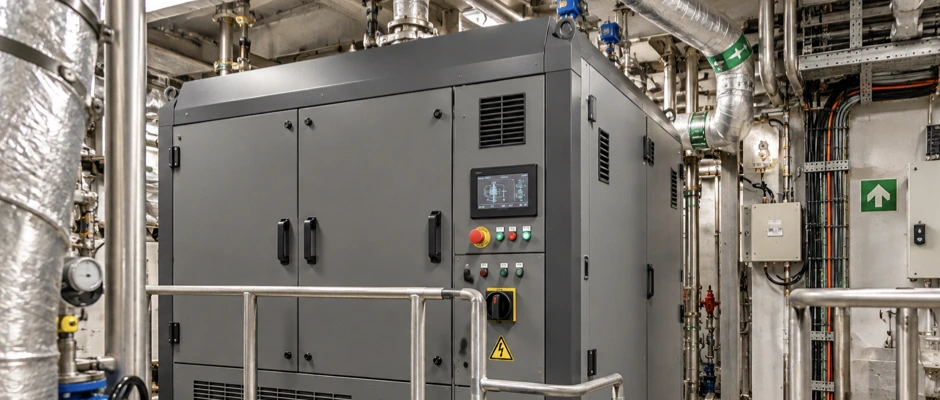
A compact ORC module may, for example, combine different components within one housing. In another design, heat exchangers, pumps or electrical equipment may be installed separately in the ship. The technical documentation must, in both cases, make sufficiently clear how the selected configuration matches the business asset description. The fact that the equipment is housed in one module or instead distributed across several locations does not remove the need for this assessment.
The origin and use of the heat also deserve attention. The specific code concerns waste heat, for which the Energy List provides its own definition. This definition does not automatically apply to all heat that a marine engine releases during operation. It must therefore be established which heat is available and currently unused in the existing ship configuration. Heat that already has a useful thermal application must not, without further assessment, be treated entirely as waste heat.
The placement of code 221102 in the Processes category also does not mean that every ORC on a ship automatically falls under this code. The Energy List also contains separate categories for investments in means of transport. For a maritime application, it must therefore be assessed which business asset code is appropriate under the applicable rules as a whole. The presence of a specific ORC code forms an important starting point in this assessment, but does not replace the assessment.
Code 221102 does not have the designation [W]. This is relevant to the relationship between specific and generic business asset codes, because the Energy List 2026 distinguishes between specifically described business assets with and without this designation. For the latter group, an application under a generic code is not ruled out merely because a specific description exists. However, the conditions of the selected generic code continue to apply in full. For a maritime ORC, it must therefore first be established whether the specific description fits and, when this is insufficiently clear, whether a generic route is possible under the applicable rules.
Why Can the Type of Expander Be Decisive for the EIA?
Not every ORC installation uses the same type of expander. In the thermodynamic cycle, the vaporized working fluid is expanded to produce mechanical power. Depending on the selected technology, a turbine or a positive-displacement expander may, for example, be used for this purpose. In certain maritime ORC installations, a screw expander is used, while the specific business asset code 221102 in the Energy List 2026 explicitly mentions a turbine.
This technical difference is important because a screw expander cannot be assumed to meet the requirement for a turbine. A supplier may correctly describe an installation as an ORC, while the expander used differs from the component named in the specific EIA description. It must therefore not be assumed solely on the basis of the term ORC that the complete installation meets code 221102. For the assessment, the expander actually used, the other cycle components and the intended purpose must be compared with the code description.
When a turbine is present and the other conditions are also met, this can form a basis for further assessment under the specific business asset code. However, the presence of a turbine does not in itself guarantee that the full investment qualifies. With a screw expander or another expansion principle, a separate assessment is needed. It is then not appropriate to state without explanation that the expander meets the code's turbine requirement.
This does not mean that every different ORC design is automatically ineligible for every EIA route. For specific business assets without [W], the Energy List 2026 also provides scope, subject to conditions, to investigate a generic business asset code. Because code 221102 is not designated with [W], a generic route may be relevant when the selected ORC does not meet the specific component description. In doing so, however, it must be established which generic category is appropriate for the particular investment.
For an ORC retrofit on an existing ship, the generic transport asset code 340000 may, for example, be worth assessing. This code imposes its own requirements on energy savings and the payback period, so the absence of a turbine does not automatically mean that code 340000 can be applied. The tax eligibility of the investing company must also be assessed separately. Changing the asset code cannot override an exclusion under the tonnage tax scheme.
When the choice of expander may have consequences for EIA classification, it is therefore advisable to discuss the technical design and possible business asset code with RVO before making the investment commitment. This can clarify which assessment route is available for that installation. The business case can then reflect the benefit only once there is enough evidence that the selected expander qualifies under the relevant EIA code.
What Is the Significance of the Definition of Waste Heat?
For the specific ORC code 221102, the concept of waste heat is important. The Energy List 2026 defines waste heat as heat that serves no useful purpose under existing operating conditions. This definition deserves particular attention on ships where engine heat is already partly used. A marine engine rejects heat through routes including exhaust gases and engine cooling water, but not all heat rejected is lost unused under current operating conditions.
Some of the engine heat may, for example, be used for steam production, hot-water production, fuel treatment or other thermal applications. When this heat already serves a useful function, it must not, without further assessment, be classified entirely as waste heat. For a new ORC, it must therefore be established which heat was actually rejected unused before the investment. For this purpose, the assessment requires a sufficiently detailed heat balance for the ship's existing systems, covering the heat sources, heat exchangers and uses of heat.
The heat balance must also show how much heat is available at the relevant engine loads and which proportion of it is already put to good use. An existing exhaust gas boiler may, for example, at a particular engine load, be able to transfer more heat than the equipment it supplies needs at that point. Under such conditions, heat may still be available that is not put to good use in the existing situation. At another engine load or with higher heat demand, the same boiler may instead need a significant proportion of the available exhaust gas heat.
The actual unused heat surplus can therefore change during operation. The assessment must therefore not be based solely on the rated power of the engine or heat exchanger, but also on when the heat supply coincides with existing demand. When a new ORC extracts heat that would otherwise be supplied to a useful thermal consumer, it may become necessary to meet that original heat demand with another energy source. This affects the actual energy savings and may raise questions about the application of the waste heat definition.
Eligibility for the deduction must be consistent with the description of the selected business asset code. A technically favourable redistribution of heat is not automatically the same as using waste heat according to that specific definition. A supplier's declaration stating only that the ORC uses waste heat from a marine engine therefore provides insufficient substantiation. For a reliable assessment, it must be clear which heat was already put to good use before the investment and which heat was actually available unused.
Can an ORC on a Ship Fall Under a Generic EIA Code?
Alongside specific business asset codes, the Energy List 2026 contains generic descriptions for investments that demonstrably save energy. For existing means of transport, code 340000 includes the category Technical Provisions for Energy Savings in or on Existing Means of Transport. A ship falls within the Energy List's definition of a means of transport, and the code lists reuse of heat through heat recovery as one possible application. Code 340000 may therefore be relevant to an ORC retrofit, but this does not mean that every maritime WHRS installation automatically meets the conditions.
The generic code imposes its own technical and financial requirements. For code 340000, the payback period must be at least five years and must not exceed fifteen years. The energy savings must also demonstrably be the direct result of the business asset concerned. For an existing means of transport, historical energy use serves as the reference, and the calculation must concern the same route and goods, assuming maximum loading as prescribed. This prevents lower fuel consumption from a different route, changed cargo or less transport work from being attributed to the ORC without further assessment.
The energy prices for this calculation are also prescribed. For electricity and natural gas, the Energy List contains specific prices that depend on the quantities consumed. For diesel use in shipping, code 340000 specifies, for 2026, a price of €0.95 per litre for the calculation. When the investment reduces use of another energy source, the prescribed treatment for it must be followed. The tax payback period calculation is therefore not automatically the same as the shipowner's commercial business case.
The two calculations may have different purposes and assumptions. A commercial assessment may, for example, include maintenance costs, emission allowances, financing and other future cash flows. The generic EIA code, by contrast, uses a prescribed calculation that divides the relevant investment costs by the annual energy cost savings. A calculation suitable for the commercial investment decision must therefore be assessed separately against the tax calculation rules.
The relationship between specific and generic business asset codes must also be assessed correctly. The Energy List 2026 stipulates that an investment corresponding in nature, use and application to a specifically described business asset included in the legislation cannot automatically be reported under a generic code. In this context, the brochure explicitly mentions an exception for specific business assets without the designation [W]. According to the explanatory notes, these are examples of generically described business assets for which the generic route may also be possible.
Code 221102 for ORC or the Kalina cycle has no [W]. The presence of this specific code therefore does not in itself constitute sufficient reason to exclude a possible notification under code 340000. However, the generic route remains dependent on the correct business asset category and evidence that all applicable requirements are met. The possibility of investigating another code therefore does not mean that the investment concerned automatically qualifies as a result.
An ORC with a screw expander may warrant assessing the generic route, though that does not in itself establish eligibility for the EIA. The tax exclusions, including any application of the tonnage tax scheme, also continue to apply. The correct choice of code must therefore be based on the actual installation and applicable conditions. Where necessary, this can be clarified with RVO before the investment commitment is made.
Which Tax Conditions Apply to the Investing Company?
The technical suitability of the ORC constitutes only one part of the EIA assessment. The company making the investment for tax purposes must also meet the conditions. The scheme is intended for qualifying businesses subject to income tax or corporate income tax. For a maritime investment, it must therefore be clear which company makes the investment commitment and how the installation is treated as a business asset for tax purposes.
The registered shipowner, technical manager and commercial operator need not be the same company. An ORC may, for example, be purchased by the shipowner while another party is responsible for day-to-day operation. Financing and leasing can also have consequences for the tax assessment. With a lease arrangement, it must be established which party invests in the business asset for tax purposes and who may, under the applicable conditions, qualify for an investment deduction. The contractual label or actual use of the installation may be insufficient to establish who qualifies.
The type of shipping activity and the way in which taxable profit is determined are also relevant. A business may carry out activities subject to the standard rules for calculating taxable profit, while other activities fall under a special scheme. For seagoing operations, the tonnage tax scheme is a particularly important consideration because it can directly affect the possibility of applying an investment deduction. The tax assessment must therefore be consistent with the investing company's activities and the way its taxable profit is calculated.
General tax exclusions for investment deductions may also be relevant. The regulations include conditions for business assets intended for use abroad or, in certain situations, made available to other parties. This deserves attention when an ORC is used on board an internationally operating ship or when several companies are involved in ownership and use. However, sailing outside Dutch waters does not automatically mean that every ORC investment falls under the exclusion for use abroad. The specific intended use, tax position and any statutory exceptions must be assessed separately for this purpose.
Neither flying the Dutch flag nor the owner's place of establishment guarantees that all tax conditions are met. The assessment must concern the company making the investment for tax purposes and the way in which the business asset is actually used. For a reliable EIA assessment, it must therefore be established which company invests, how it is treated for tax purposes and which specific exclusions may be relevant to the installation concerned.
Why Is the Tonnage Tax Scheme Particularly Important for Sea Shipping Companies?
The Dutch tonnage tax scheme is an important consideration for investments in energy-saving installations on board seagoing ships. Under this scheme, taxable profit from qualifying seagoing activities is calculated on a deemed basis using the ships' tonnage. Taxable profit then does not follow from actual revenue and costs in the same way as under the regular profit calculation. The tonnage tax scheme therefore also has consequences for the application of certain tax deductions.
The Dutch Tax Administration states that there is no entitlement to an investment deduction for the part of the business to which the tonnage tax scheme applies. This may directly determine the tax treatment of an ORC installation. A waste heat recovery system may technically meet a business asset description in the Energy List but still yield no EIA benefit when the investment is attributable to the part of the business covered by the tonnage tax scheme. The technical suitability of the ORC and the tax treatment of the company must therefore be assessed separately.
Checking only whether the technology appears in the Energy List provides insufficient certainty for a company operating seagoing ships. It must also be clear whether the installation belongs to a shipping activity whose taxable profit is determined under the tonnage tax scheme. For companies carrying out different activities, a separate assessment may be necessary for this purpose. A shipping company may, for example, alongside certain seagoing activities, have other business activities to which the standard rules for calculating taxable profit apply.
However, this does not mean that an investment can be attributed at will to an activity outside the tonnage tax scheme. The allocation must reflect the actual function, ownership and use of the business asset and to the applicable tax rules. Nor is every company operating seagoing ships automatically subject to the tonnage tax scheme. The scheme has its own eligibility criteria and applies on request once the Tax Administration has approved it. It therefore cannot be stated generally that maritime ORC investments in the Netherlands are always excluded from the EIA.
When the ORC investment belongs to the part of the business covered by the tonnage tax scheme, there is no entitlement to an investment deduction for it. If the investment falls outside that part, it must still be assessed whether all other technical, tax and procedural EIA conditions are fulfilled. For companies operating seagoing ships, this assessment may be decisive for the financial business case. A potential tax benefit must therefore not be treated as a guaranteed cash saving when the tonnage tax scheme excludes application of the deduction.
Which ORC Investment Costs May Qualify for the EIA?
When the installation and the investing company meet the conditions in principle, it must be determined which costs form part of the investment amount eligible for the EIA. The full WHRS retrofit investment is not automatically equal to the amount eligible for the Energy Investment Allowance. The EIA concerns the qualifying costs of the business asset and certain necessary provisions associated with it. These may include the acquisition costs of the relevant ORC equipment.
Provisions that are technically necessary for the business asset concerned and are used exclusively for it may also qualify under the applicable conditions. For an ORC, this may, for example, be relevant to certain pipes, fittings and instrumentation and controls. In addition, costs paid to third parties to make the qualifying business asset ready for operation, such as certain installation costs, may form part of the acquisition costs. In this context, the assessment must be consistent with the actual work and its relationship to the business asset concerned.
Production costs are the costs a business incurs when it makes or installs an asset under its own management. Under the applicable conditions, these may include labour costs, contracted work and materials from their own stock. Which cost category applies depends on how the work is carried out and how the commitment or costs arise. Acquisition costs and production costs must therefore remain sufficiently identifiable in the accounts.
A general alteration of the engine room is not automatically attributable in full to the ORC. Nor may work serving existing engine, cooling or electrical systems be treated, without sufficient substantiation, as exclusively necessary parts of the qualifying business asset. In a retrofit, foundations, heat exchangers, pumps and electrical connections may, for example, be needed. Whether their costs actually qualify for the EIA depends on the business asset code applied and the conditions that apply to the provisions concerned.
In addition, a distinction must be made between investment costs and maintenance costs. Routine maintenance costs do not qualify as an EIA investment, even when this work is necessary to keep the installation in good condition during operation. Moreover, the business asset must in principle be new, because the EIA is not intended for the ordinary purchase of previously used business assets. Under certain circumstances, however, the RVO conditions do allow certain costs for previously used components within a new business asset.
This distinction may be relevant when a new ORC is connected to existing ship installations. The presence of existing cooling water pipes or pumps does not automatically make a new ORC a used business asset. Conversely, costs of existing equipment may not be included again as new investment expenditure. The cost breakdown must therefore make sufficiently clear which components are being purchased new and which were already present on the ship.
VAT must also be treated correctly. When the investing company can recover the VAT paid, the amount reported for the EIA generally excludes that VAT. When the VAT cannot be recovered, it may form part of the qualifying costs under the applicable conditions. The company's tax position is therefore also a factor in determining the correct cost breakdown.
For 2026, a minimum investment of €2,500 per business asset also applies. RVO also sets a minimum for the total amount reported for commitments and production costs. The financial documentation must therefore distinguish sufficiently between qualifying equipment, necessary additional provisions and other project costs. A higher total WHRS project investment does not automatically mean that the EIA basis increases in the same proportion.
When Must an ORC Investment Be Notified for the EIA?
The notification deadline is an important procedural condition for applying the EIA. For acquisition costs, the investment must in principle be notified to RVO within three months of making the investment commitment. The relevant date is therefore not automatically the day on which the equipment is delivered, invoiced or paid for. An investment commitment may, for example, arise when a binding order is placed or a purchase agreement is concluded.
For a maritime ORC, there may be a considerable period between making this commitment and the actual delivery or installation on board. The module may still have to be manufactured, while the ship-specific engineering and preparations for installation at the yard are already taking place. When an entrepreneur only investigates whether the EIA is possible after commissioning, the deadline for notifying the original acquisition costs may already have passed. It is therefore advisable to check tax eligibility and the applicable business asset code before the order is placed.
Different notification periods apply to production costs. When the business incurs qualifying costs for work under its own management to manufacture or install a business asset, these must in principle be notified within three months after the end of the calendar quarter in which they were incurred. When the business asset enters service in the same quarter, the deadline for notifying those production costs is three months after entry into service. These differences may be relevant to an ORC retrofit in which the main equipment is purchased and additional installation components are fitted under the entrepreneur's own direction.
However, not every installation invoice automatically falls under the tax category of production costs. The nature of the work, the agreements with the parties carrying it out and the time at which costs or commitments arise determine which notification rules apply. Acquisition costs and any production costs must therefore be distinguished sufficiently clearly in the project accounts. This allows the business to identify the deadline for each cost category based on the relevant event.
The Energy List for the correct investment year must also be applied. For acquisition costs, the relevant year is generally the year in which the investment commitment is made. An order in 2026 with delivery in 2027 therefore does not automatically mean that the Energy List 2027 applies to that purchase commitment. For production costs, the rules that correspond to the costs concerned and the time at which they arise apply.
The EIA notification is submitted digitally to RVO. If the notification is late, the tax benefit may be lost. The notification must therefore be aligned with the actual contractual and financial events within the project. Relying solely on the planned date on which the ORC is first brought into operation provides insufficient certainty about the correct notification period.
How Does the EIA Tax Benefit Work in 2026?
For 2026, the Energy Investment Allowance allows a deduction equal to 40% of the qualifying investment amount. This percentage relates to an additional deduction from taxable profit. It is therefore neither a direct subsidy of 40% of the purchase price nor a guaranteed tax reduction of 40% of the investment. When the company meets the conditions, it may deduct an additional 40% of the established qualifying investment amount from taxable profit. This additional deduction is in principle available alongside the usual tax depreciation under the rules applicable to it.
The actual tax benefit then depends on the company's tax position. For a company, the applicable corporate income tax rate may, for example, be relevant, while different tax considerations may apply to a business owner subject to income tax. The availability of taxable profit also affects the time at which the benefit can be used. A company without sufficient taxable profit does not automatically receive the full tax benefit as an immediate cash payment.
Under the applicable rules, losses may be carried back or forward where the applicable rules allow. However, the actual financial value and timing must be established for the company concerned. For investments that have not yet entered service, a restriction may also apply based on the amounts actually paid in the tax year concerned. For an ORC project with a long lead time or payments in several instalments, this may be relevant to the year in which the deduction can be claimed.
A distinction must therefore be made between making the investment commitment, timely notification to RVO and the time at which the tax deduction can actually be used. These events need not take place in the same calendar year. After an EIA notification, RVO assesses whether the investment falls within the scheme and how much of the investment qualifies. Following a positive assessment, the business receives an EIA declaration and can then report the deduction in its tax return.
The Tax Administration remains responsible for the tax treatment of the return. An EIA declaration therefore does not automatically mean that all other tax questions have been resolved, such as the application of the tonnage tax scheme or certain general exclusions for investment deductions. The technical assessment by RVO and the Tax Administration's treatment of the claim must therefore be sufficiently distinguished from one another. Both are relevant to establishing whether the expected benefit can actually be realized.
The interaction with other schemes also deserves attention. Under certain conditions, the EIA can be combined with the small-scale investment allowance. By contrast, the EIA and the environmental investment allowance cannot be applied simultaneously to the same investment costs. When an investment is relevant to both schemes, the business must select one scheme or make a permitted allocation of costs between them. Certain subsidies may also have consequences for the qualifying investment amount or for the possibility of applying the EIA.
For the financial assessment, the full original investment amount must therefore not be assumed without further checking. It must first be established which costs qualify, which schemes can be applied and which tax benefit the company can actually use. The actual EIA benefit follows from these combined conditions and the entrepreneur's tax position. The deduction percentage of 40% forms only one part of the final financial calculation.
Which Documentation Is Needed to Substantiate EIA Eligibility?
For an ORC investment, sufficiently clear technical and financial data are needed to assess the applicable EIA conditions. The technical documentation must show which installation is being purchased, its components and intended use. In an assessment under code 221102, the actual configuration must be compared with the specific business asset description. In this context, the condenser, evaporator, pump and type of expander are among the relevant components.
When a turbine is used, this must be evident from the technical specifications. Where a screw expander or another type of expander is used, it must be established which business asset code is appropriate for the actual design. The origin and existing use of the heat must also be sufficiently clear. For the specific ORC code, after all, it must be possible to assess whether the heat used meets the applicable definition of waste heat.
For this purpose, data on engine load, heat sources, existing thermal consumers and intended heat extraction may be needed. An overview of the existing heat and energy balance can help establish which heat was discharged unused before the investment. When a ship already uses recovered heat, this must also be evident from the documentation. In this way, a distinction can be made between existing heat use and the additional application for which the ORC is being purchased.
When a generic transport asset code is being considered, additional data are needed. The Energy List then requires, among other things, a calculation of the energy savings and a payback period according to the prescribed method. For this purpose, the historical energy data and relevant reference conditions must be sufficiently reliable. For an existing means of transport, these must be consistent with the prescribed comparison using the same route and goods, with both cases assuming maximum loading.
A commercial payback period calculation incorporating, for example, emission costs, maintenance or financing terms need not automatically comply with the prescribed tax calculation method. The calculation used for the EIA must therefore remain separately identifiable. It must also be clear which energy prices and investment costs may be used under the code concerned. In this way, a commercially attractive ORC is prevented from being classified as a qualifying business asset without further tax substantiation.
The financial documentation must also be consistent with the notification. Orders and purchase agreements are important for establishing when the investment commitment arose. Invoices, payment details and the cost breakdown must identify the equipment and provisions that may form part of the qualifying investment. In this context, it must be clear which costs relate directly to the business asset concerned and which concern other ship modifications.
For production costs, work carried out under the entrepreneur's own direction, materials and other relevant cost categories must be sufficiently identifiable. The time at which these costs were incurred may also be important for the applicable notification period. In addition, it must be clear which company is making the investment for tax purposes. When the owner, manager, leasing company and commercial operator are different companies, additional documentation on ownership, financing and use may be necessary.
For companies operating seagoing ships, it must also be established whether the tonnage tax scheme applies. This tax assessment may be decisive, regardless of whether the ORC technically meets a business asset description. A general supplier's declaration that an ORC saves energy or is eligible for the EIA therefore does not automatically provide sufficient certainty. The technical design, selected business asset code, investment costs, notification details and the company's tax position must be assessed together to make sufficiently clear on what basis the investment may qualify for the EIA.
When Can the EIA Be Reliably Included in the ORC Business Case?
The Energy Investment Allowance may provide an additional financial benefit when an ORC investment meets both the technical and the tax conditions. For the business case, this potential benefit must be distinguished from the actual energy savings. The direct savings from waste heat recovery arise when the ORC produces useful electricity and thereby displaces existing generation. The lower fuel consumption and its financial value depend on the available heat supply, the net ORC output and the ship's actual operation.
An EIA benefit has a different origin. It arises only when the investment falls under a permitted business asset code and the investing company can actually use the tax deduction. For this purpose, the technical classification must first have been sufficiently established. It must also be clear whether the heat used meets the waste heat definition under the specific code and whether the selected expander matches the relevant component description. When a generic route is considered, the investment must meet that code's own technical conditions and payback period requirements.
The investor's tax position must then be examined. For companies operating seagoing ships, the tonnage tax scheme is particularly relevant because there is no entitlement to an investment deduction for the part of the business to which this scheme applies. The qualifying investment costs and notification periods must also be sufficiently clear. Not every expense needed for a complete WHRS retrofit automatically constitutes a qualifying EIA investment.
Only when these conditions have been assessed can the potential tax benefit be estimated reliably. When the applicability of the selected code or the company's tax position is still uncertain, the business case must not treat the EIA as a confirmed tax benefit. The same applies when the financial value is based solely on the deduction percentage. After all, an EIA of 40% does not mean that the ORC investment becomes 40% cheaper.
The actual benefit depends on taxable profit, the relevant tax rate, the qualifying costs and the time at which the deduction can be processed for tax purposes. For an investment implemented over several years, the timing of payments and entry into service may also have consequences for the tax cash flows. The financial assessment must therefore be consistent with the time at which the entrepreneur is expected to be able to use the benefit in practice. Confirmation that the investment qualifies and realization of the tax benefit need not take place in the same period.
A future sale of the business asset may also be relevant. When the ORC is disposed of within the statutory disposal period, an investment allowance recapture may arise under certain conditions. This deserves attention when the owner expects to sell the ship or installation relatively soon after the investment. Any tax benefit at purchase must then be assessed in conjunction with possible tax consequences of the later disposal.
For a sound investment decision, a distinction therefore remains between the technical energy savings, the potential EIA amount and the tax savings that can actually be realized by the investing company. When tax eligibility is still insufficiently established, the WHRS investment can also be assessed without the assumed EIA benefit. A tax benefit confirmed later can then be included as additional financial value. In this way, economic feasibility is prevented from being made dependent on a tax benefit whose applicability has not yet been sufficiently substantiated.
When Is an ORC Installation on Board Actually Eligible for the EIA?
An ORC installation on a ship may qualify for the Energy Investment Allowance when the investment meets the requirements of an applicable asset code in the Energy List and the investing company meets the other tax and procedural conditions. For 2026, the Energy List contains a specific description for Organic Rankine Cycle or Kalina cycle under code 221102. When this code is applied, the installation must be used for the stated purpose and include the required components.
The description mentions, among other components, a turbine. For an ORC with a screw expander or another expander, it must therefore be assessed whether the selected design can be accepted within the specific description. The definition of waste heat also remains important. To the extent required by the selected code, the heat used must meet the applicable conditions. According to the Energy List, waste heat is heat that served no useful purpose under existing operating conditions.
When the installation does not fit the specific code, a generic business asset code may be investigated under certain conditions. Because code 221102 has no [W], the Energy List 2026 does not exclude a generic route solely because this specific ORC code is present. For an existing ship installation, code 340000 may be relevant, provided that the actual investment fits within that means-of-transport category. The prescribed payback period requirement of at least five and no more than fifteen years must then also be met, among other conditions.
However, the technical choice of code must be assessed separately from the investing company's tax position. Particularly for companies operating seagoing ships, the tonnage tax scheme may be decisive. There is no entitlement to an investment deduction for the part of the business to which this scheme is applied. An ORC that technically fits the Energy List therefore does not automatically provide an EIA benefit for every shipping company.
When the company and the installation can in principle qualify, the eligible investment costs must then be established and the investment must be notified to RVO on time. For acquisition costs, a notification period of three months after the investment commitment is made applies in principle. Separate deadlines apply to production costs, corresponding to the nature and timing of the costs concerned. A careful assessment therefore preferably takes place before a binding order is placed or other significant investment commitments are made.
The EIA eligibility of a maritime ORC is ultimately determined by the combination of the correct business asset code, the technical design, the use of waste heat where required, the investor's tax position, the qualifying costs and correct notification. Only when these conditions have been sufficiently established can the expected tax benefit be reliably included in the business case for an ORC-based waste heat recovery system on board.
This Article Within the Series
The EIA can make an ORC investment more attractive for tax purposes, but only when both the installation and the investing company meet the conditions. This potential tax benefit is separate from the additional fuel savings with existing heat use, which must be established without double counting. How these savings, the full project costs and any tax benefits together determine the investment outcome is addressed in the economic feasibility of waste heat recovery and within the business case and investment decision for WHRS installations.